Blogs /

Many fund managers are hearing “no” more often than they expected.
Not because their deals are weak.
Not because investors have lost interest in private markets.
But because investors are asking sharper questions and reacting faster when clarity is missing.
Across private markets, investor selectivity has increased. Yet those rejections are rarely random. In most cases, they follow consistent patterns tied not to opportunity quality, but to how a fund is structured, explained, and experienced.
The distinction we keep seeing is simple:
Investors aren’t rejecting funds.
They’re rejecting confusion.
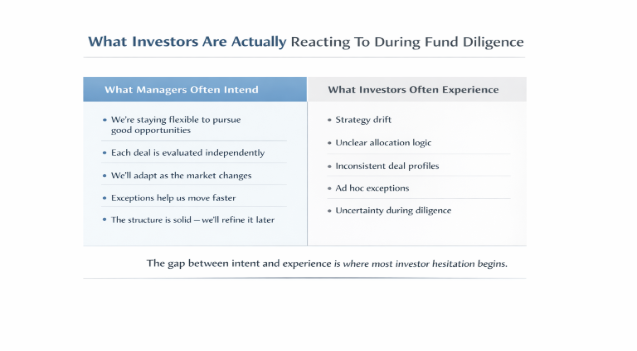
Investor feedback often sounds vague:
“We’re not sure it’s the right fit.”
“Let’s revisit this later.”
“We want to see how this develops.”
But those responses usually point to something specific uncovered during diligence.
Common Friction Points Include:
None of these mean a fund is the wrong structure.
They signal that the fund experience isn’t as clear or repeatable as investors expect.
Funds remain the professional, scalable vehicle for raising capital. Friction emerges when a fund’s design no longer reflects how capital is actually raised or deployed.
We See This When:
In these cases, the fund isn’t failing.
The design is fighting the strategy.
That tension is often what investors feel, even when they can’t articulate it directly.
When investors lean in, it’s because they can see beyond the first deal.
Confidence Increases When They Experience:
Investors don’t want rigidity.
They want repeatability: a clear sense of how decisions will scale, not just how the first investment works.
Funds perform best when flexibility is built into the structure, not added later.
Well-designed Funds:
When this happens, the fund becomes infrastructure, not paperwork.
And this is often where capital raising regains momentum.
A simple way to assess whether structure is helping or hurting:
If several of these feel unclear, investors are likely sensing it as well.
Across 500+ capital raisers we’ve worked with, the same pattern appears:
Momentum returns when the structure stops fighting the strategy.
Clarity returns when:
This is also why many managers eventually move away from purely deal-by-deal approaches as they scale. We explored that transition in Why Raising Capital Deal-by-Deal Might Be Slowing You Down.
👉 Why Raising Capital Deal-by-Deal Might Be Slowing You Down
Hearing “no” doesn’t mean funds no longer work.
More often, it’s feedback on how a fund is designed, communicated, or executed.
The question isn’t:
“Should I raise a fund?”
It’s:
“Is my fund designed to support how I raise capital today and where I’m going next?”
As private markets become more disciplined, clarity and structure are becoming advantages, not overhead.
At Avestor, we work with fund managers across strategies and stages to pressure-test fund design before it becomes a point of friction during diligence. Many of the patterns described above are conversations we have every day, often before a manager decides whether to restructure, evolve, or scale their existing fund.
If you’re thinking through how your current fund structure supports where you’re headed next, comparing notes with other managers can bring clarity faster than doing it in isolation.
We’re always open to sharing what we’re seeing across the platform and the questions investors are asking most often today.
We believe clarity builds confidence. Here are answers to some of the most common questions we receive from sponsors, fund managers, and investors navigating private offerings.
Get in touch with us today!
Contact Us